When Youth Banking Gets Real: Why Middle School Matters
Middle school is when kids start wanting more independence, including with money. For credit unions and banks, those moments are an opportunity to build relationships that grow with them.
Middleschool changes more than a kid’s schedule.
Teens start asking for more independence. Friends matter more. Interests shift. They start figuring out who they are, and who they wantto become.
Money changes, too.
A kid who once thought, “Mom gave me $10,” starts thinking, “I earned $10.” Then: “It’s my money.” And eventually: “What should I do with it?”
There are moments when a young person starts figuring outwhat money means to them, and what they can do with it.
For credit unions and banks, that’s an opportunity farbigger than opening another youth account. It’s an opportunity to be there whileit’s happening.
Why Middle School Is When It Starts
In middle school, kids stop just getting money. They start wanting a say in what happens to it.
They aren't financially independent yet. They shouldn't be. But they're starting to want more ownership over the choices they make.
The first time they earn.
A chore. Babysitting. Helping a neighbor. Selling something.The amount doesn't matter. The feeling does. “I earned this.”
That's ownership.
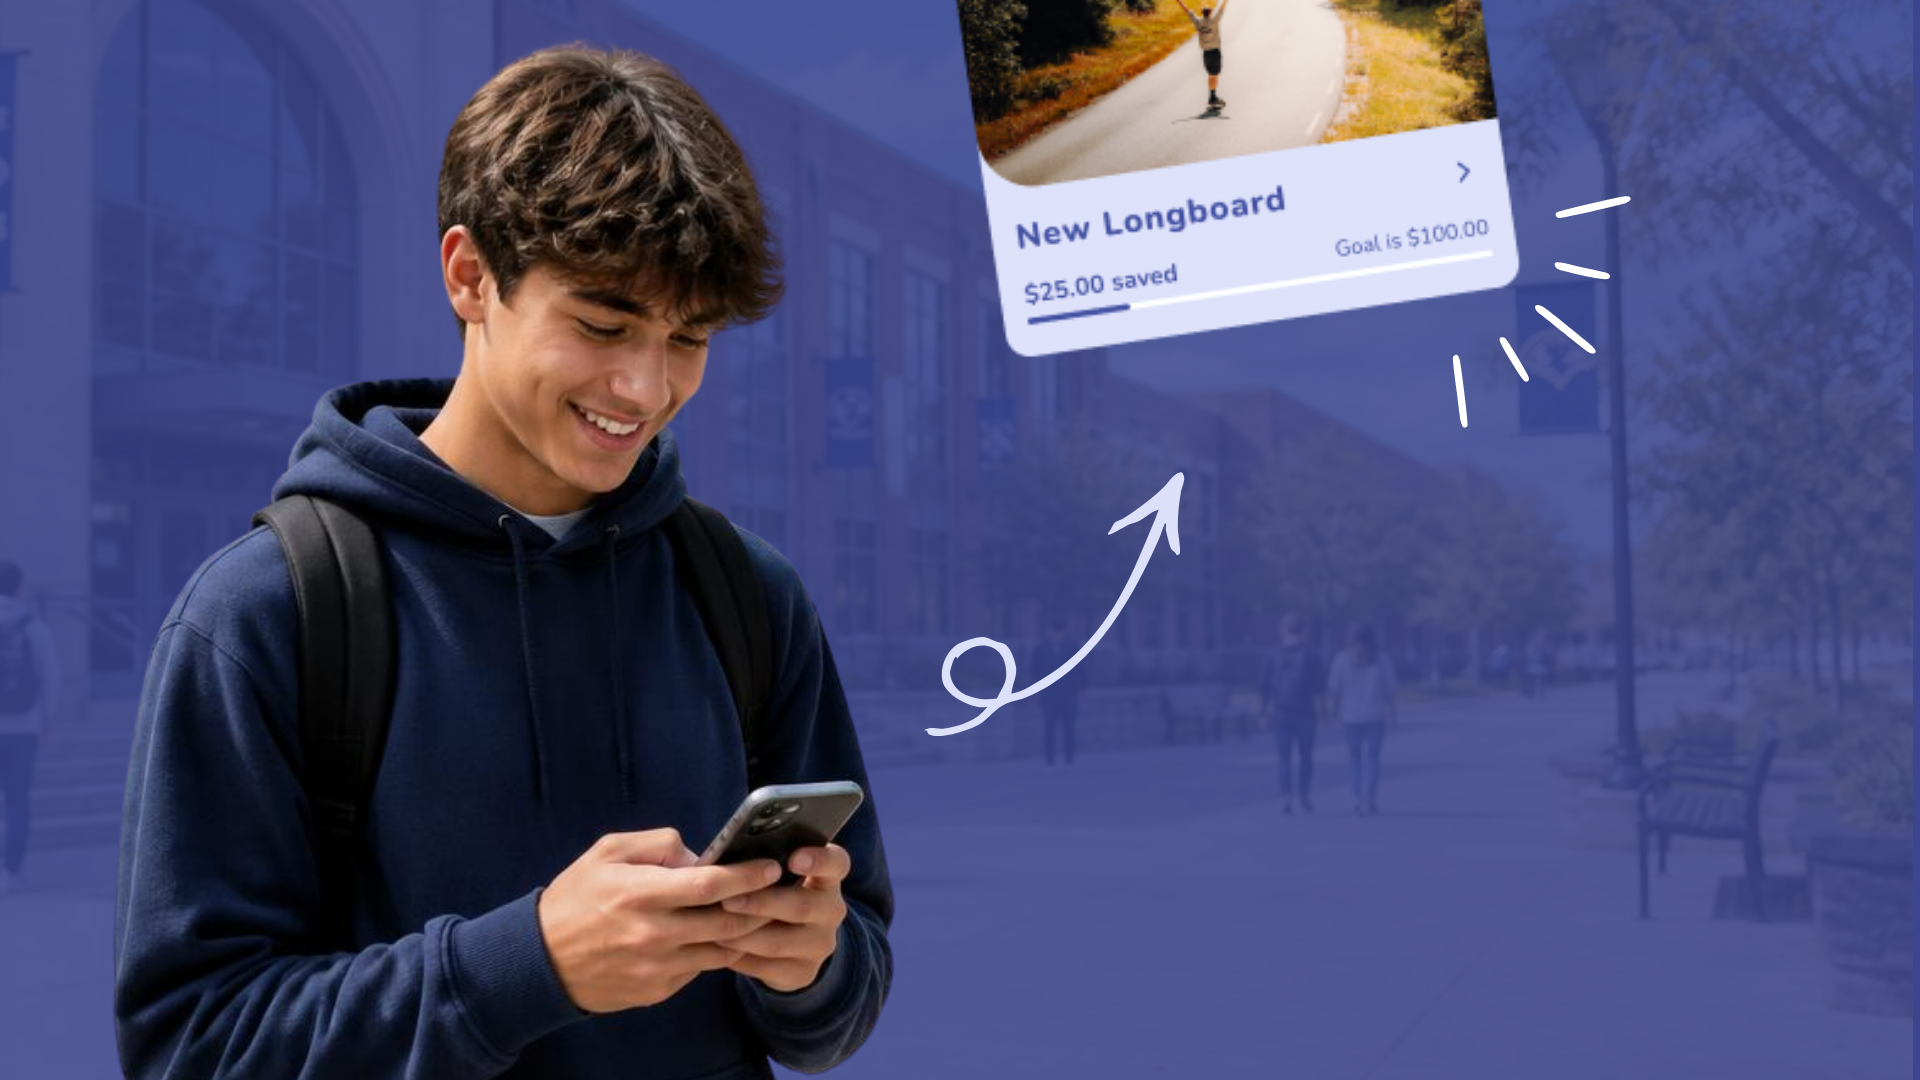
The first time they save for something they really want.
This is different from being told to save. They have a goal.They make a choice. They watch their money get closer.
That's planning.
The first time they spend their own money.
Maybe it's something small. But the thought changes: “This was my decision.”
That's autonomy.
The first time they run out of money.
Painful? A little. But it’s also a moment they’re unlikely to forget. They made a choice. They saw the result. Next time, they might choose differently.
That's learning.
The first time they make a mistake.
Financial confidence isn't built by making sure kids nevermake mistakes. It's built by giving them room to make manageable ones,understand what happened, and try again, with the right guardrails in place.
That's how confidence grows.
What About the Parents?
Kids aren't the only ones in transition. Parents are learning, too.
At 10, a parent might approve every purchase.
At 15, they might set the limits and check in.
By 18, the goal is to step back.
That's a pretty big shift.
The parent goes from “I'll handle it” to “Let's figure it out” to “What do you think?” to, eventually, “You've got this.”
The best family banking experience doesn't take parents outof the equation. It helps them change roles as their kid grows.
Parents still get visibility. They still set guardrails.They still get to step in when it matters.
But the kid gets something important, too: A little room to figure things out.
Is a Youth Account Enough?
Opening a youth account is a starting point. But what makes it valuable is everything that happens after the account is opened.
A young person needs a reason to come back. Something to do with the money. Something to work toward. A little more responsibility as they grow.
Maybe it starts with an allowance. Then a savings goal. Thena first debit card. Eventually, a paycheck, a bigger purchase, and more decisions they can make on their own.
The account grows with them.
And that’s where youth banking gets interesting. The goal isn’t simply to give a young person access to a bank account. It’s to create anexperience that becomes more relevant as they become more independent.
For the institution, that changes the relationship, too.
Instead of showing up only when an account is opened, the financial institution has a reason to be part of the journey, through the small decisions, new milestones, changing needs, and growing independence that happen along the way.
And for credit unions and banks, that may be the bigger opportunity: not just attracting the next generation, but giving them a reasonto stay.
Where Family Banking Fits
That's the real opportunity behind family banking. Not just giving a kid an account. Giving them a place to practice.
A place to earn.
A place to save.
A place to make a choice.
A place to make a mistake.
And a place to try again.
The kid gets an experience built for them. The parent gets the tools and visibility to guide them. And the credit union stays part of the relationship as that kid grows up.
Because the goal isn't just to hand a young person a bank account. It's to help them build a relationship with money, and with their financial institution that grows with them.
That's what Boucoup was built for. Boucoup is a white-label family banking platform that helps credit unions and community banks bring kids, teens, and parents into one connected experience, under their own brand.
The Small Moments Aren't Small
The first savings goal may seem small. The first purchase may seem insignificant. The first mistake may seem forgettable. But these are the moments when young people start answering bigger questions:
Can I make good decisions?
Can I manage something of my own?
Can I work toward something I want?
Can I learn from a mistake?
Those aren't transactions. They're the building blocks offinancial confidence.
For credit unions and banks, being there for these momentsis how a relationship starts.
You don’t build a lifelong financial relationship in onetransaction. You build it one moment at a time.
Be there for the first. Stay for what’s next.

Welcome to our blog on all things BankingON and our perspective on what's going on in the Credit Union and Banking Industry. If you get a chance, share our posts on social media!
Featured Posts