How Does an 18-Year-Old's Youth Account Actually Convert to an Adult Account?
Opening a youth account is easy. Keeping the relationship at 18 is harder. The key is creating a clear path from youth banking into adult banking. Here's what that can look like.
It's one of the most recurring questions credit unions and banks ask when evaluating a youth banking platform.
Because opening the youth account is only the beginning.
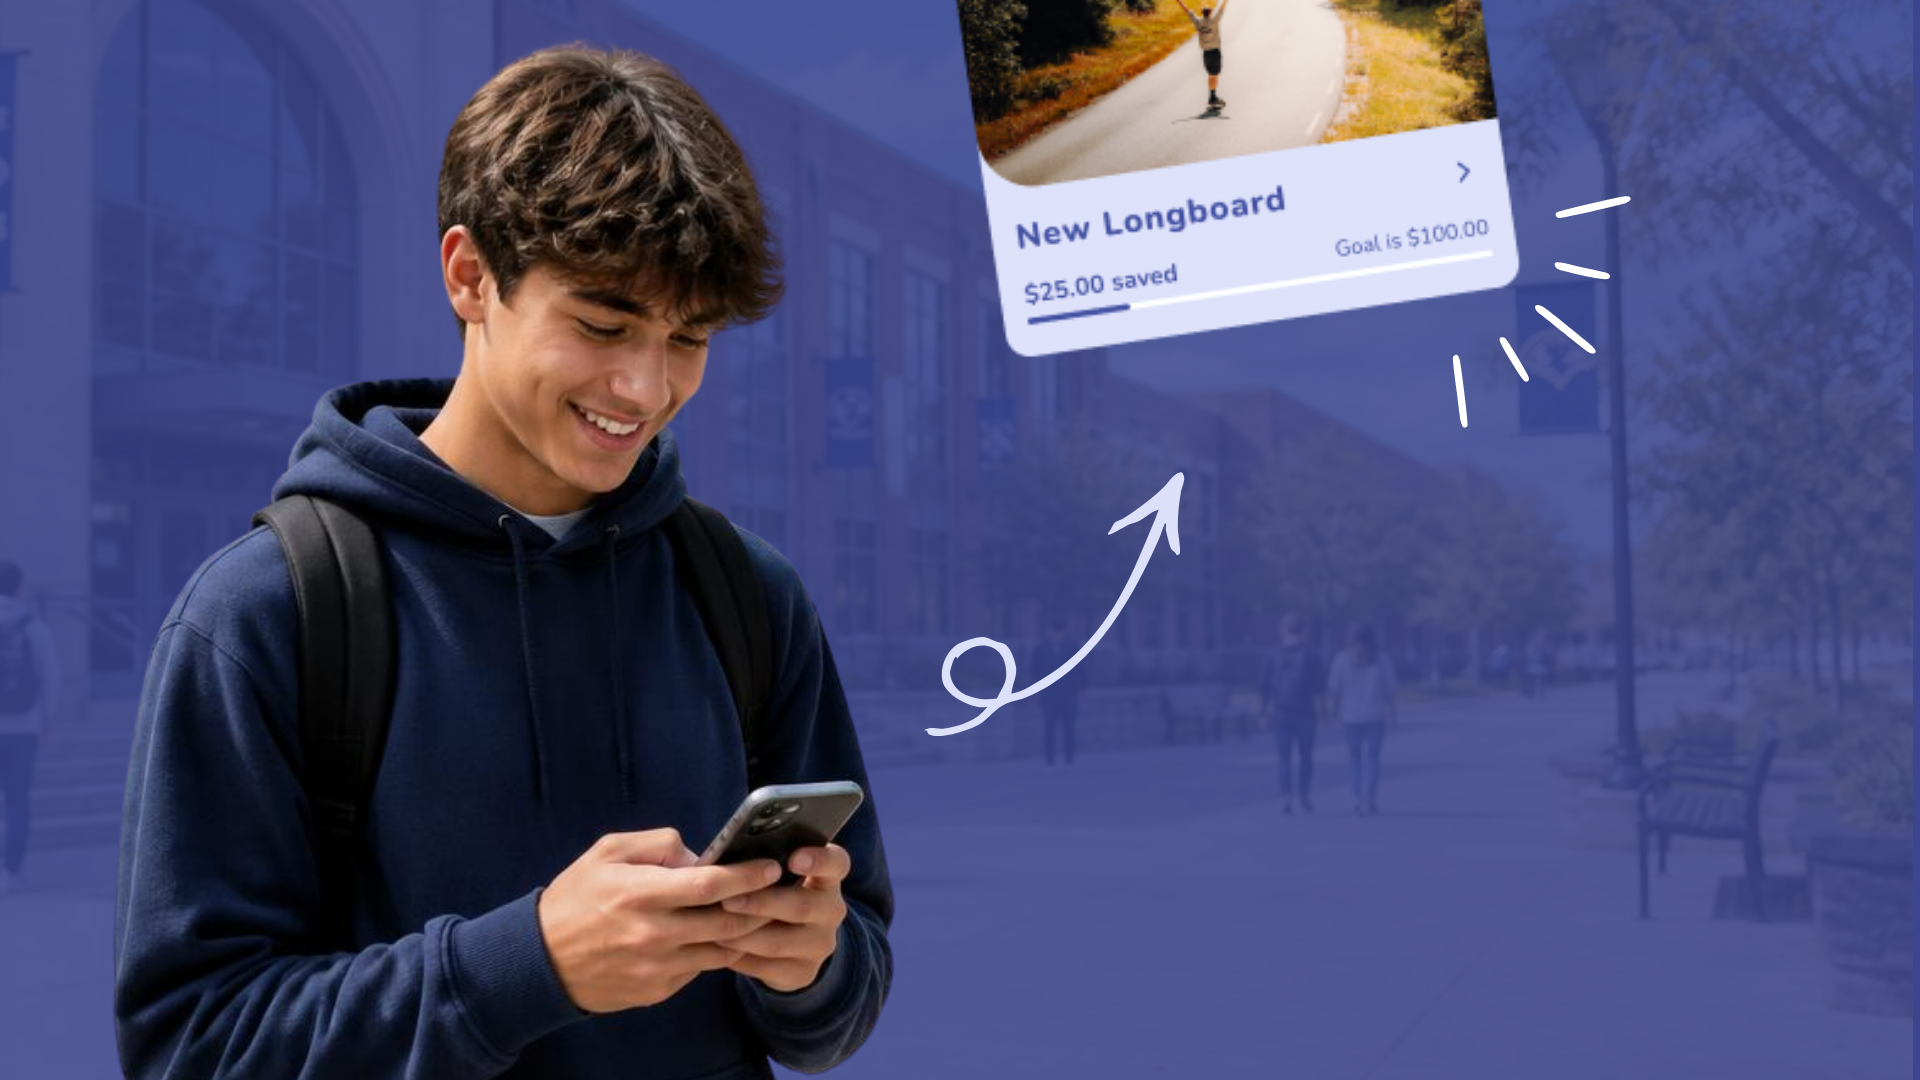
At 10, a young person might be learning how to save forsomething they want. At 14, they're spending an allowance. At 16, they'regetting their first job. At 18, they're ready to start building credit with afinancial institution.
And suddenly, that "youth banking" relationship isn't so youth anymore. That's when many young people have to move to another product, or, worse, another financial institution.
Not because the relationship wasn't valuable, but because the youth account wasn't designed to lead naturally into adult banking.
What "Conversion" Usually Means in Practice
For a lot of youth banking products, there isn't really a conversion. There's an ending.
The youth account was built around a debit card, parental controls, savings tools, and a way for parents to help their kids learn about money.
Then the young person grows up.
They need a checking account. They start earning a paycheck.They want their first credit card. They need to start building credit.
So they move into a different product, and that's where the relationship can break.
If the transition feels like starting over, the young person has every reason to look somewhere else for what's next.
A new app. A new credit card. A new banking relationship.
The institution helped them get started. Someone else gets to help them grow.
Why 18 Is Such an Important Moment
At 18, a young adult is ready for a very different kind of banking relationship.But from a traditional lending perspective, they're often a thin-file customer.
- Little or no credit history.
- Limited income.
- Not much borrowing history.
That can make a first credit card or loan difficult to evaluate. And here's the frustrating part:
The financial institution may have been part of that young person's financial life for years. But a traditional credit file doesn't show everything that happened before 18.
It doesn't show how they learned to save, how they managed spending, whether they made payments on time, how they handled a balance, or whether they practiced managing a loan before real credit was on the line.
The relationship may be years old. The credit history maybe brand new.
What a Real Conversion Looks Like Instead
A youth banking platform built for the whole financial relationship treats 18 as a graduation, not a wall. That starts years earlier.
Every practice loan managed, every chore completed, every savings goal hit, every financial mistake learned from, all of it cancontribute to a richer behavioral history inside the same relationship, longbefore a credit application ever gets filled out.
By the time that young person turns 18, the financial institution isn't starting from a blank slate. It has had years of opportunities to see how this specific young person interacts with money.
That's what makes the transition feel like a seamless graduation instead of a restart.
The young person moves from Teen, learning by doing with a debit card, allowances, savings goals, and practice, into young adult, moving into adult banking, their first credit card, and building real credit history.
The app changes. The relationship doesn't have to.
What This Actually Requires From a Platform
For a conversion to work this way, three things have to be true.
1. Their financial history shouldn't start over at 18
The young person shouldn't suddenly become a stranger to the institution on their 18th birthday.
Their financial experiences (saving, spending, practice loans, payments, and other activity) should remain part of the relationship and give the institution meaningful context as they move into adult banking.
2. The transition has to be proactive
Graduation shouldn't come as a surprise.
The young person and their parents should know what's coming and understand what happens next.
3. Turning 18 should open the next door
Turning 18 shouldn't simply change an account status.
It should open the door to the products that make sense for the next stage of life, whether that's checking, a first credit card,credit-building opportunities, or eventually loans.
And because the institution has been part of the young person's financial journey for years, that conversation can start from a placeof familiarity rather than a cold application.
How Boucoup Helps Make It Possible
This is where Boucoup's approach to youth banking matters. Boucoup is built around learning by doing.
Young people don't just learn about money.
- They use it
- They save
- They spend
- They earn
- They manage balances
- They make payments
- They make decisions
And with Boucoup's practice loans, they canexperience the responsibility of managing a loan while parents remain incontrol.
Over time, those experiences create something valuable: a financial relationship that has been developing for years before the first adult banking application.
Then They Graduate
When the young person is ready for adult banking, they move from the Boucoup experience into the financial institution's adult banking app.
They're ready for a different experience.
✓ More independence
✓ More responsibility
✓ New financial products
✓ And potentially, their first real credit relationship
But they don't have to start the relationship from scratch.
The Real Test
Anyone can help a child open a youth account. The real question is: What happens when they grow up?
If the relationship ends, you've built a youth product.
If it grows with them, you've built a path to a life time relationship.
That's what Boucoup is built to do: start early, build financial confidence, and create a natural path into adult banking.
See how Boucoup helps financial institutions build relationships that grow →

Welcome to our blog on all things BankingON and our perspective on what's going on in the Credit Union and Banking Industry. If you get a chance, share our posts on social media!
Featured Posts